Questions About Using Your VREB Reward to Buy Down Your Rate
Understand discount points, potential payment savings and what needs to be confirmed before closing.
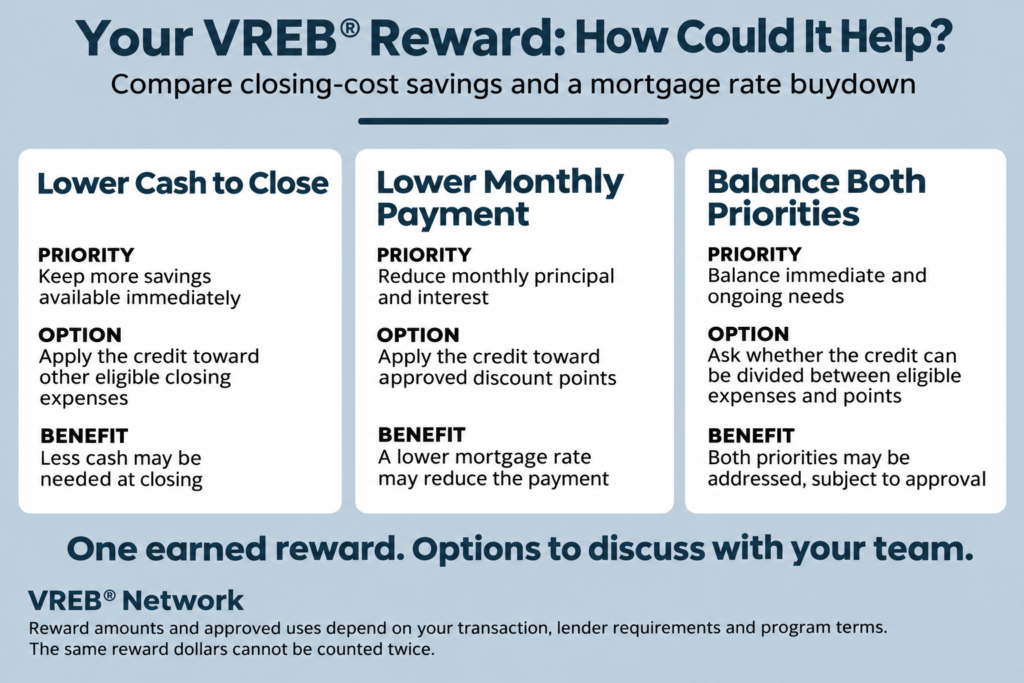
It may be possible when the reward is approved for eligible discount points. Your VREB team, lender and closing professionals must confirm the available amount and permitted use for your transaction.
No. One point costs 1% of the loan amount. The interest rate reduction offered in exchange varies by lender, loan and market pricing.
Yes. Reasonable discount points are permitted on VA-backed loans. Your lender determines the pricing and must review any proposed VREB reward credit.
Not necessarily. The result depends on the cost of the points, monthly savings and how long you keep the loan. Compare those figures before choosing.
No. Discount points lower the loan’s interest rate. A temporary buydown uses funds to cover part of the scheduled payments for a limited period. Ask your lender which arrangement is being offered.
Possibly. Ask whether the approved credit can be allocated between eligible points and other expenses. The same reward amount cannot be applied twice.
No. You may use your own lender. However, that lender must review and coordinate any proposed use of your reward at closing.
Receiving the reward afterward does not change the interest rate already established at closing. Discuss any proposed rate buydown before your loan closes.