Can You Use Your VREB Reward to Buy Down Your Mortgage Rate?

Put Your VREB Reward Toward Potential Mortgage Savings

Your VREB® reward may be applied toward a mortgage rate buydown when approved for your transaction. Through eligible discount points, a lower interest rate may be secured at closing. As a result, your reward could help reduce your monthly principal and interest payment. However, the available credit, point cost and loan requirements must be confirmed before this option is included in your purchase plan.

What Does Buying Down Your Mortgage Rate Mean?

A mortgage rate buydown can involve paying discount points at closing in exchange for a lower interest rate.

One discount point costs 1% of your loan amount. Therefore, on a $300,000 mortgage, one point would cost $3,000.

However, one point does not mean your interest rate drops by one percentage point. The reduction depends on your lender, loan and available pricing. Ask for quotes with and without points so the difference can be reviewed. Consumer Financial Protection Bureau

How Your VREB Reward May Help With Discount Points

Rather than paying the entire cost of eligible points from your own savings, an approved VREB reward credit may help cover that expense.

First, discuss the option with your VREB team and assigned agent. Your lender and closing team can then confirm whether the reward may be applied toward points and how the credit must be documented.

For the broader explanation, explore the VREB reward closing-cost credit.

Compare Lower Closing Costs With a Lower Mortgage Rate

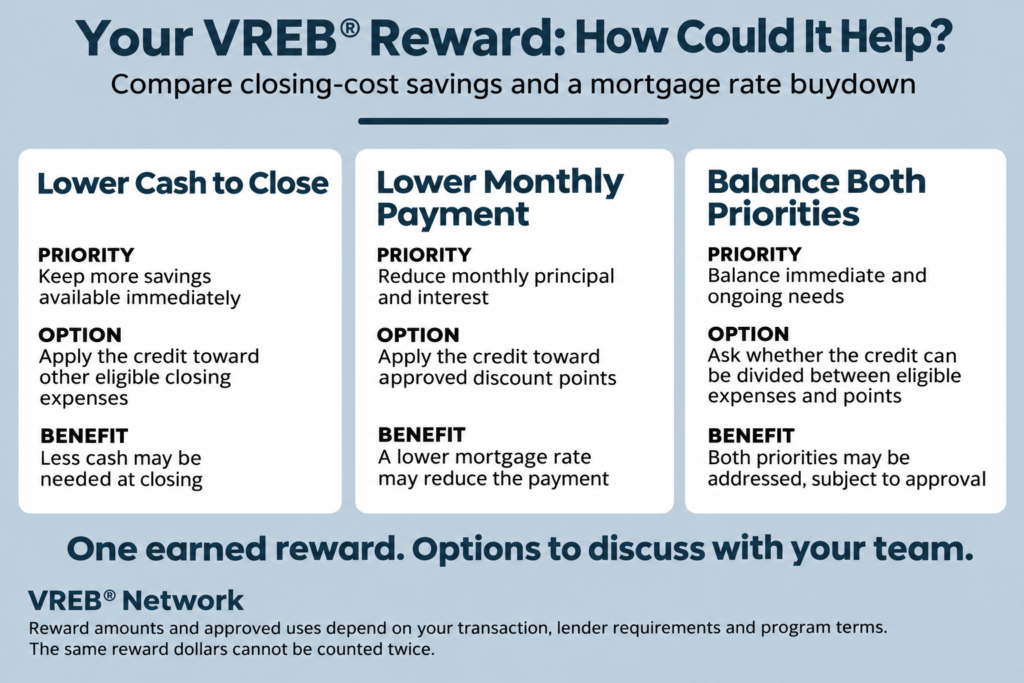
Your reward may support different priorities, depending on how the approved credit is used.

VREB reward comparison showing options for lower closing costs, a mortgage rate buydown or dividing an approved credit between both.

The same reward dollars cannot be counted twice. Consequently, ask your team to show how each proposed allocation affects your closing funds and monthly payment.

Read more about the immediate benefit: how your VREB reward can reduce out-of-pocket closing costs.

Understand the Break-Even Period

A lower monthly payment should be considered alongside the upfront cost of obtaining it.

A simple break-even estimate is calculated by dividing the cost of the discount points by the monthly principal and interest savings.

Consider this hypothetical example:

A Simple Break-Even Example

Divide the cost of discount points by the monthly principal and interest savings to estimate the break-even period.

Comparison Amount
Cost of discount points $2,400
Monthly principal and interest savings $60
Simple break-even period 40 months

$2,400 ÷ $60 per month = 40 months

Hypothetical example only. These figures are not a rate quote or a prediction of savings. Actual costs, savings and reward eligibility depend on your loan and transaction.

In this example, approximately 40 months of savings would equal the cost of the points.

Even when your reward covers that cost, it remains useful to compare the savings with another approved use of the reward. If the loan is refinanced or paid off earlier, less time would be available to benefit from the lower rate.

These figures illustrate the calculation only. They are not a rate quote or a prediction of your savings.

Confirm Your Buydown Options Before Closing

Discount points can lower the interest rate for the life of a fixed-rate mortgage. By comparison, a temporary buydown covers part of your payments for a limited period before the full scheduled payment becomes your responsibility.

Reasonable discount points are permitted on VA-backed loans. However, pricing is set by your lender, and your proposed VREB® reward credit must be approved separately. Availability for a temporary buydown should also be confirmed.

Before choosing, request a comparison of the rate, point cost, monthly payment, cash needed at closing and break-even period. Consider how long you expect to keep the loan. Additionally, remember that taxes and insurance may change even when your principal and interest payment remains fixed.

Questions About Using Your VREB Reward to Buy Down Your Rate

Understand discount points, potential payment savings and what needs to be confirmed before closing.

It may be possible when the reward is approved for eligible discount points. Your VREB team, lender and closing professionals must confirm the available amount and permitted use for your transaction.

No. One point costs 1% of the loan amount. The interest rate reduction offered in exchange varies by lender, loan and market pricing.

Yes. Reasonable discount points are permitted on VA-backed loans. Your lender determines the pricing and must review any proposed VREB reward credit.

Not necessarily. The result depends on the cost of the points, monthly savings and how long you keep the loan. Compare those figures before choosing.

No. Discount points lower the loan’s interest rate. A temporary buydown uses funds to cover part of the scheduled payments for a limited period. Ask your lender which arrangement is being offered.

Possibly. Ask whether the approved credit can be allocated between eligible points and other expenses. The same reward amount cannot be applied twice.

No. You may use your own lender. However, that lender must review and coordinate any proposed use of your reward at closing.

Receiving the reward afterward does not change the interest rate already established at closing. Discuss any proposed rate buydown before your loan closes.

The Benefits of Choosing VREB Network

Through VREB® Network, your agent connection and potential reward can be considered together while your purchase is being planned.

Eligible members may earn up to $10,000 through a qualifying transaction, subject to program terms. Depending on approval, that reward may help with eligible closing expenses or a mortgage rate buydown.

You can also use your own lender. As a result, available loan options can be compared while your VREB® team helps explain the reward requirements.

For buyers, the benefit is a coordinated conversation about the home purchase, available reward and how that reward could support their budget. VREB® Network

Explore How Your VREB Reward Could Work for You

Before deciding between lower closing expenses and potential monthly savings, find out what is available for your purchase.

Explore Your VREB® Rate Buydown Options and ask your team to review the possibilities with your lender.


Registration and a qualifying transaction through a VREB-assigned agent are required. Reward amounts and approved uses vary by transaction, state rules, lender requirements and program terms. Additional conditions are provided in your VREB® Membership Agreement.

get started

Please fill out the form below.

HOMETOWN HEROES

What location you are looking to buy or sell your home?(Required)